23-10-2026
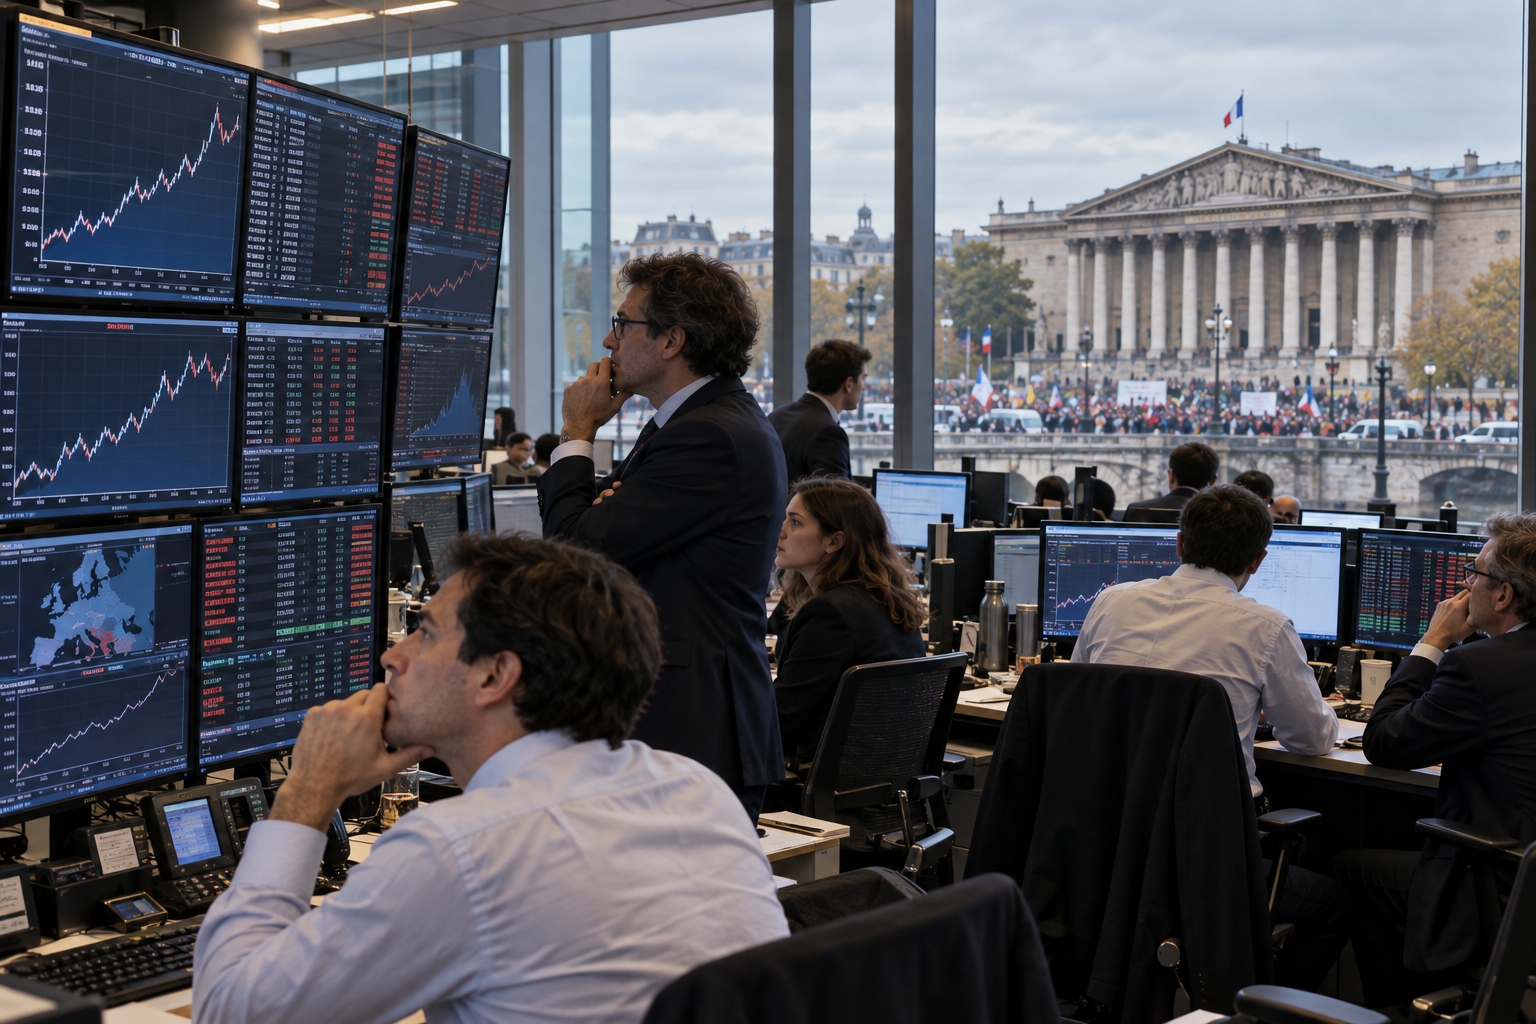
France’s rising borrowing costs and widening bond-yield spread over Germany have revived concerns that the country’s fiscal problems could spill into the wider euro zone. The 10-year French bond yield climbed above 5% for the first time since 2002, while the French-German spread exceeded 170 basis points and the cost of insuring French debt reached its highest level since the early-2010s debt crisis. The euro has also weakened against the dollar.
France faces a large and growing public debt, one of the euro area’s highest deficit-to-GDP ratios, sluggish growth, political instability and social unrest. The government has cut its 2026 growth forecast to 0.5%. Analysts say market distrust and uncertainty are making investors wary, though some consider the situation primarily a French risk rather than an imminent threat to the euro area as a whole.
The article compares current pressures with the crisis that began in Greece and spread to Portugal, Ireland, Italy and Spain. That episode involved stressed sovereign debt, vulnerable banks and a feedback loop in which rising borrowing costs worsened government finances. Nobel laureate Paul Krugman warns that higher interest costs can reinforce fears of default and capital flight.
Views differ on how severe France’s situation is. Some analysts describe it as a crisis already, citing a debt-to-GDP ratio of 119%. Others argue that a broad spillover remains limited: France’s financial problems are known, unlike Greece’s dramatic 2009 deficit revision, and euro-area banks and institutions are stronger and have more tools to contain fragmentation. BlackRock nevertheless cautions that volatility and spillovers remain possible. Analysts say a wider spread could raise borrowing costs in Italy and Spain and provoke political backlash. Overall, the article presents significant French fiscal and political risks, but a repeat of the early-2010s systemic crisis is considered less likely.
Entities: France, Euro zone sovereign debt crisis, French-German 10-year bond yield spread, Government debt and fiscal deficits, Sovereign fragmentation and contagion • Tone: analytical • Sentiment: negative • Intent: analyze
23-10-2026
France’s escalating government-bond sell-off is tightening borrowing conditions across the eurozone just as the European Central Bank prepares to decide on interest rates. The ECB is widely expected to hold rates next week: rising bond yields are already restraining economic activity, and ING economist Carsten Brzeski estimates that the increase in German yields has had an effect comparable to a 25-basis-point rate hike, and the French increase closer to 50 basis points. He expects the ECB to wait for new forecasts in December before considering another hike.
France’s 10-year bond yield has risen above 5% for the first time since 2002, while its spread over German bonds has widened substantially. The cost of insuring against a French government default has also climbed to its highest level since 2012. Investors face political and fiscal uncertainty: lawmakers are divided over a budget proposing €43 billion in cuts and revenue measures, a Moody’s downgrade is widely expected, and protests and union mobilisation are adding to concerns. France’s debt-to-GDP ratio stands at 119.1%, and the government expects debt-servicing costs to rise by more than €10 billion in 2027 compared with this year.
ECB President Christine Lagarde has stressed that France must address its debt problems through domestic fiscal policy rather than expect a rescue from Frankfurt. Officials have not ruled out intervention, but say the conditions are not currently met. One possible tool, the Transmission Protection Instrument, allows bond purchases when borrowing costs are judged unjustified and threaten monetary-policy transmission; eligibility requires compliance with fiscal rules and sustainable debt. France’s budget outlook may make it difficult to qualify. Another tool, Outright Monetary Transactions, requires a government to accept a bailout programme. Brzeski sees a flexible pause in reducing the ECB’s bond holdings as more likely for now, with the TPI a last resort if turmoil spreads. He describes the coming meeting as likely to be “uneventful on action but clearly not on words.”
Entities: European Central Bank (ECB), France, Christine Lagarde, Carsten Brzeski, ING • Tone: analytical • Sentiment: negative • Intent: analyze
23-10-2026
The France 24 item previews a Moody’s credit-rating decision on France, with a downgrade described as widely expected amid growing concerns about the country’s public debt. The article connects those concerns with cost-of-living protests, noting that France is struggling with increasing public debt while public demonstrations are taking place. It also reports that the yield on France’s 10-year government bonds has risen above 5% for the first time since 2002. The higher yield means the government faces more expensive borrowing, underscoring the financial pressure behind the debate over the country’s public finances.
The segment features Oliver Davis, identified as a professor and Head of the French Department at University College Cork, as a guest. The supplied text does not include his remarks or further details about Moody’s assessment, the scale or timing of a possible downgrade, or the government’s response. It therefore presents the issue as a news discussion rather than providing a full account of the rating agency’s reasoning or policy options.
Overall, the item links a prospective credit downgrade and rising borrowing costs to France’s worsening debt concerns, while placing these developments alongside domestic protests over the cost of living. Its central message is that public-finance worries have become more acute as the bond yield reaches a level not seen in over two decades. The content provided is a brief description of a video segment; the surrounding related-story links and website notices do not add reporting details to this specific item.
Entities: France, Moody’s, Oliver Davis, University College Cork, French Department • Tone: analytical • Sentiment: negative • Intent: inform